I travel a lot, but I definitely don’t pay full price for every flight.
A huge part of how I’m able to travel as much as I do comes down to credit card points, airline miles, and knowing when to move points from one program to another.
I’m not doing anything particularly complicated. I don’t have 25 credit cards, I’m not constantly manufactured-spending my way to bonuses, and I don’t spend hours calculating the value of every single point.
I’ve just built a system around expenses I was already going to have.
And over time, those points add up to a lot of flights.
First: “almost free” isn’t completely free
Before we go any further, points tickets usually aren’t literally free.
You’ll generally still pay some combination of taxes, airport fees and sometimes airline surcharges.
There are also the annual fees on some of the credit cards I use.
So when I say I travel “almost for free,” what I really mean is that I’ve been able to replace thousands of dollars in airfare with points and miles I earned from spending I was already doing.
That distinction matters.
I don’t use the same credit card for everything
This is probably the easiest thing you can change if you want to start earning more points.
Different cards reward different types of spending.
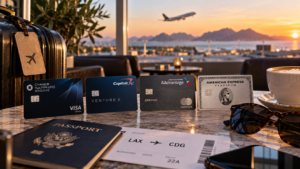
My Chase Sapphire Reserve is especially useful for travel and dining. It currently earns 4x points on flights and hotels booked directly, 3x on dining and 8x on travel booked through Chase Travel.
Then I have my Capital One Venture X, which I love for purchases that don’t fall into some exciting bonus category.
It earns 2x miles on basically everything, plus 10x on hotels and rental cars and 5x on flights and vacation rentals when booked through Capital One Travel.
So instead of putting everything on one card, I try to use the card that earns me the most for that purchase.
It doesn’t seem dramatic when you’re buying dinner or booking one hotel.
Do it all year and it adds up.
But earning the points is only half of it
This is probably the biggest thing I learned about points.
I usually don’t want to just spend Chase points as Chase points or Capital One miles as Capital One miles.
Both programs allow you to transfer your points to airline loyalty programs. Chase partners with programs including Air France/KLM Flying Blue, Air Canada Aeroplan, United, Virgin Atlantic and others. Capital One also has a large group of airline partners, including Flying Blue.
That’s where things get much more interesting.
Instead of thinking:
“I have 80,000 Chase points.”
I think:
“Which airline program can get me where I’m going for the fewest points?”
Sometimes the answer isn’t even the airline I’m going to fly.
One of my favorites: Flying Blue
I transfer a lot of points to Flying Blue, the loyalty program for Air France and KLM.
And one of my favorite uses of Flying Blue miles is actually booking Delta flights.
Yes, Delta.
Because Delta is a Flying Blue partner, Flying Blue miles can be used to book eligible Delta-operated flights when award seats are available. You search through Air France, KLM or Flying Blue rather than booking directly through Delta.
I’ve used this strategy for flights between the U.S. and Europe.
So I might earn the original points from Chase or Capital One, transfer them to Flying Blue, and then use those Flying Blue miles to sit on a Delta airplane.
This is the part of points and miles that initially feels confusing.
The airline whose plane you’re sitting on doesn’t necessarily have to be the program whose miles you used to book it.
Once that clicks, you suddenly have many more options.
I use American Airlines miles differently
I also keep an American Airlines AAdvantage account and an AA credit card.
Those miles are useful to me for South America.
American has a large group of partner airlines where AAdvantage miles can potentially be redeemed, including its oneworld partners as well as airlines like GOL and JetSMART, which gives me additional options when traveling around South America.
For example, American and GOL currently allow AAdvantage members to redeem miles on eligible GOL flights.
So again, I’m not thinking:
American miles = American Airlines flight.
I’m thinking:
American miles = access to the whole network of flights I can book with them.
That mindset makes miles much more useful.
I even earn Delta miles from Airbnb
This is one of those tiny things that sounds almost pointless until you realize how much money you spend on accommodation over a year of traveling.
Delta has a partnership with Airbnb.
When I activate the Delta/Airbnb offer and book an eligible Airbnb Home, I can earn 1 Delta SkyMile for every eligible $1 spent. Airbnb Experiences and Services currently earn 3 miles per eligible dollar. Taxes and certain fees don’t earn miles.
So if I’m going to spend $1,500 on an Airbnb anyway, why wouldn’t I take another 1,500 Delta miles?
One thing to know: Delta’s current system requires you to activate the partnership through deltaairbnb.com, and the booking eligibility currently lasts 10 days before you need to renew it. So I check it again before booking rather than assuming it’s permanently connected.
This is basically how I think about points in general.
If I’m spending the money anyway, I want something back from it.
I don’t transfer points until I know what I’m booking
This is important.
I usually keep flexible points with Chase or Capital One until I’m ready to use them.
Then I search award availability.
Once I find the flight I want, then I transfer.
Why?
Because once you transfer Chase points to an airline, for example, the transfer is final. You can’t simply change your mind and move those Flying Blue miles back into Chase.
Flexible points give me options.
Airline miles lock me into that airline program.
So I don’t move 100,000 points into Flying Blue just because I might go to Europe six months from now.
I wait until I see something worth booking.
I also check the cash price first
Points aren’t automatically a good deal.
If a flight costs $150, I’m probably not going to burn a huge number of miles just because I can.
But when a long-haul ticket is $1,200, $1,500 or more and I can cover most of it with points?
Now I’m interested.
The same goes for transfer bonuses.
Sometimes Chase or Capital One offers a bonus for transferring points to a certain airline program. That can make an already good redemption much better.
But I never transfer just because there’s a bonus.
I want a trip first. Then I figure out the points.
Not the other way around.
My basic system is actually pretty simple
This is essentially what I do:
1. Earn flexible points from everyday spending.
I use different cards depending on what earns the most points.
2. Keep those points flexible.
I generally leave Chase points with Chase and Capital One miles with Capital One until I have a reason to transfer them.
3. Search airline partners, not just the airline I want to fly.
If I want a Delta flight to Europe, I check Flying Blue too.
If I’m traveling around South America, I look at what I can access through AAdvantage and its partners.
4. Transfer only when I find a redemption worth booking.
Then I move the points and book.
5. Collect the little miles too.
Airbnb partnerships, airline shopping offers, card spending: individually they might not look like much.
Over a year, they become another flight.
You don’t need ten credit cards to start
Points and miles can get absurdly complicated online.
People talk about transfer ratios, award charts, positioning flights, fifth-freedom routes and cents-per-point valuations until traveling starts sounding like accounting.
You really don’t need to start there.
Start with one good flexible travel card.
Learn where its points can transfer.
Pick one airline program you actually use.
And start paying attention to where your normal spending is earning rewards.
Once you understand that, you can add complexity if it actually helps you.
The biggest rule: never spend money just to earn points
This entire strategy only works if you’re paying your credit cards off.
If you start carrying a balance and paying 20%+ interest because you’re chasing airline miles, the math falls apart very quickly.
I don’t buy things because they earn points.
I earn points because I was already going to buy those things.
There’s a big difference.
Why I bother with all of this
Because travel is easily one of my biggest expenses.
And every flight I can book with points is money I can use somewhere else — staying longer, choosing a better hotel, going to another country, or simply spending less.
Over time, I stopped seeing credit card points as little rewards.
I see them as another currency.
Chase points become Flying Blue miles.
Flying Blue miles become a Delta flight to Europe.
American miles become a partner flight through South America.
An Airbnb stay quietly adds more Delta miles to the pile.
And eventually all of those little decisions turn into another plane ticket.
That’s basically how I keep going somewhere.
The cards I use
I currently earn most of my flexible travel points through the Chase Sapphire Reserve. If you want to know more read The Travel Credit Cards I Actually Use →
Credit card rewards, transfer partners and loyalty-program rules change frequently. Always verify current terms with the card issuer or airline before transferring points or applying for a card. This article reflects my personal strategy and experience and isn’t financial advice.